Your Rate Didn’t Change. So, Why Can’t You Afford Your Home Anymore?
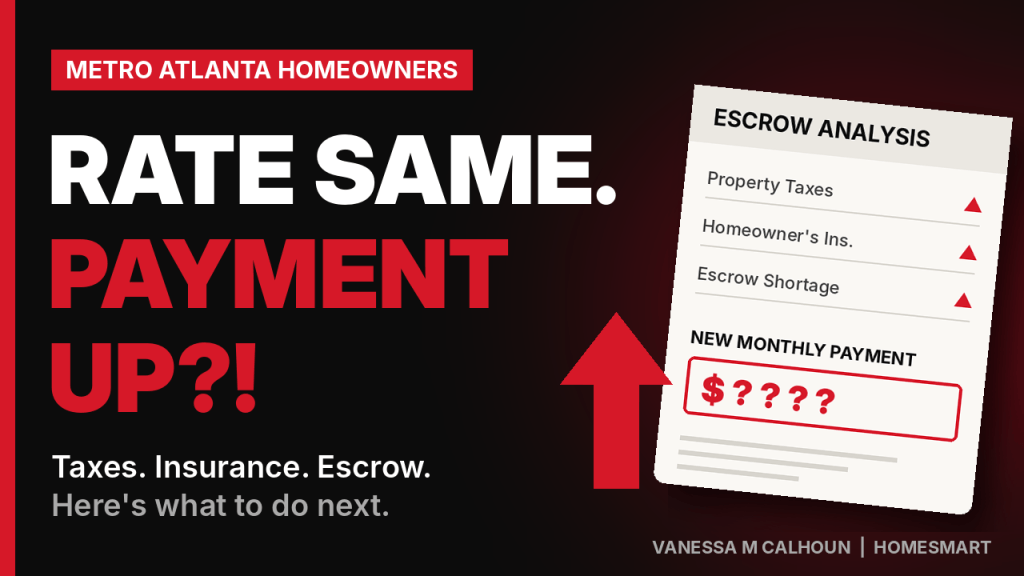
Why did my mortgage payment increase when my interest rate remained the same? In Metro Atlanta, a higher payment on a fixed-rate loan usually comes from escrow: your property taxes, homeowner’s insurance, or both increased.
Picture this…You open a letter from your mortgage servicer on a regular Tuesday afternoon. You haven’t refinanced, you haven’t missed a payment, and you locked your rate years ago. However, the letter states your monthly payment will soon increase.
Many Metro Atlanta & Cobb County homeowners are receiving that letter right now….and it can feel like the ground has shifted right under your feet.
I want to tell you about clients of mine who went through this. Then, I’ll walk you through what you can do so their story doesn’t become yours.
WHAT HAPPENED TO MY CLIENTS?
My clients were responsible homeowners. They paid on time, kept up the house, and planned their budget around a payment they could manage.
Then, two things happened at once. Their property taxes increased, and their income decreased.
Same house. Same interest rate. But the monthly payment no longer fit into their lives.
So, they did what most of us would do. They tried to refinance. After all was said and done, the refinance would save them $127/ mo….definitely not enough to keep them afloat.
That’s real money, and in a different situation, it might have been enough. However, when your costs are climbing and your income is simultaneously shrinking, a small savings can’t close that kind of gap.
In the end, they made the difficult decision to sell.
I’m sharing their story because it can happen to anyone, and because it happens quietly, nobody plans for the year when taxes rise and paychecks shrink in the same season.
WHY DOES MY PAYMENT CHANGE WHEN MY RATE DOESN’T?
Most homeowners with a mortgage pay more than principal and interest each month. Your payment usually includes an escrow account, which your servicer uses to pay your property taxes and homeowner’s insurance for you.
Your rate may be locked, but those escrow costs are not. Once a year, your servicer reviews the account. When taxes or insurance increases, they raise your monthly payment to cover the difference. When the account comes up “short”, they may add the “shortage” amount on top.
So, when discussing affordability in Metro Atlanta or Cobb County, we simply can’t stop at the interest rate.
WHAT CAN I DO TO PROTECT MYSELF?
You have more control than you may think! Here are three steps I recommend to every homeowner I work with:
1. Read your escrow statement line by line
Don’t toss that letter in the drawer…look at exactly what’s changed:
- Did your property tax bill increase?
- Did your insurance premium increase at renewal?
- Is there a one-time shortage, or did your ongoing payment increase?
Knowing which cost changed tells you where to focus. Many servicers will also let you spread a shortage over 12 months instead of paying it all at once, so do not be afraid to ask.
2. Appeal your property assessment when the notice comes
In Georgia, your county mails an annual assessment notice, usually in the spring. You generally have 45 days from the notice date to file an appeal.
When the value on that notice looks higher than what your home would actually sell for, an appeal is worth considering. Recent comparable sales within your neighborhood are some of the strongest evidence you can bring. (This is where a local agent can help, by the way.)
And make sure your homestead exemption is in place. If you’re military or over the age of 65, be sure to check for other exemptions that may apply to you. An exemption is one of the simplest ways to lower your tax bill as a Georgia homeowner. Your county tax commissioner’s website will have the details.
3. Shop your homeowner’s insurance every year
This one surprises people. Many homeowners set up their insurance at closing and never look at it again. Meanwhile, the premium creeps up year after year.
Shopping your policy each year is one of the easiest ways to take back some control. Similar coverage can come with very different price tags from one company to the next.
When you compare quotes, look at more than the premium:
- Coverage limits: Is your dwelling coverage enough to rebuild your home?
- Deductible: A lower premium with a much higher deductible may cost you more when you file a claim.
- What’s excluded: Make sure you understand what isn’t covered.
WHAT IF I’VE ALREADY TRIED ALL OF THAT?
Sometimes, the numbers just don’t work anymore. That’s exactly what happened with my clients.
When that’s where you are, the most important thing to do is to speak with someone early. While you’re still current on your payments, you have choices. You may be able to sell on your own timeline, protect your equity, and move into something that fits your life today.
The longer you wait, the fewer choices you have. Selling isn’t a failure. Sometimes, it’s the decision that sets up your next chapter.
BUYERS, THIS PART IS FOR YOU…
If you’re shopping for a home in Metro Atlanta or Cobb County, here’s the lesson I want you to take from my clients’ story:
Don’t buy at the top of what you’re approved for.
Your pre-approval tells you the most a lender may let you borrow. It doesn’t tell you what’s comfortable for your life.
Choose a payment that lets you keep saving long after you’ve signed your closing documents. Leave room in your budget for:
- Property taxes that may rise over time
- Insurance premiums that may increase at renewal
- Repairs and maintenance
- Life changes, like a job change or income reduction
The goal isn’t just to buy a home. It’s to keep it, and to enjoy living in it without feeling stretched every month.
WHAT DOES THIS MEAN FOR METRO ATLANTA HOMEOWNERS?
We’re in a market where owning a home costs more than the mortgage alone. Taxes and insurance are now a BIG party of the conversation, and we need to plan for them the same way we plan for the interest rate.
The good news? Homeowners who stay informed and act early have options. Review your escrow, check your assessment, shop your insurance, and run your numbers before a letter forces the decision for you.
Frequently Asked Questions
Why did my mortgage payment increased on a fixed-rate loan? A fixed rate locks your principal and interest, but your escrow can still change. Increases in property taxes or homeowner’s insurance are the most common reasons your total payment goes up.
How do I appeal my property taxes in Georgia? Your county mails an annual assessment notice, and you generally have 45 days from the notice date to file an appeal with your county’s board of assessors. Recent comparable home sales are strong evidence of your home’s market value.
How often should I shop my homeowner’s insurance? Reviewing your policy and comparing quotes once a year, ideally before your renewal date, is a smart habit. Compare coverage limits and decuctibles, not only the premium.
Let’s Look at Your Numbers Together
Don’t wait for the letter that changes everything. Call or text me at 470-209-8136 and let’s look at your numbers together while you still have options on the table. Whether you’re a homeowner feeling the squeeze or a buyer who wants to get it right from day one, I’m here to help you make a plan that works for your life.
Vanessa M Calhoun, B.S., Associate Broker | REALTOR®️ | HomeSmart | Metro Atlanta/ Cobb County | Cell: 470-209-8136 | Office: 404-876-4901 | vcalhounrealestate@gmail.com
Your Next Chapter Starts With a Conversation…


Leave a Reply